
Lincolns Webinar | Free Online Event
Let’s Talk Tax: CGT, Trusts and What Might Be Changing
There’s a lot of noise around the latest tax changes, so let’s talk about what they could actually mean.
Thursday 26 November 2026
Reserve your place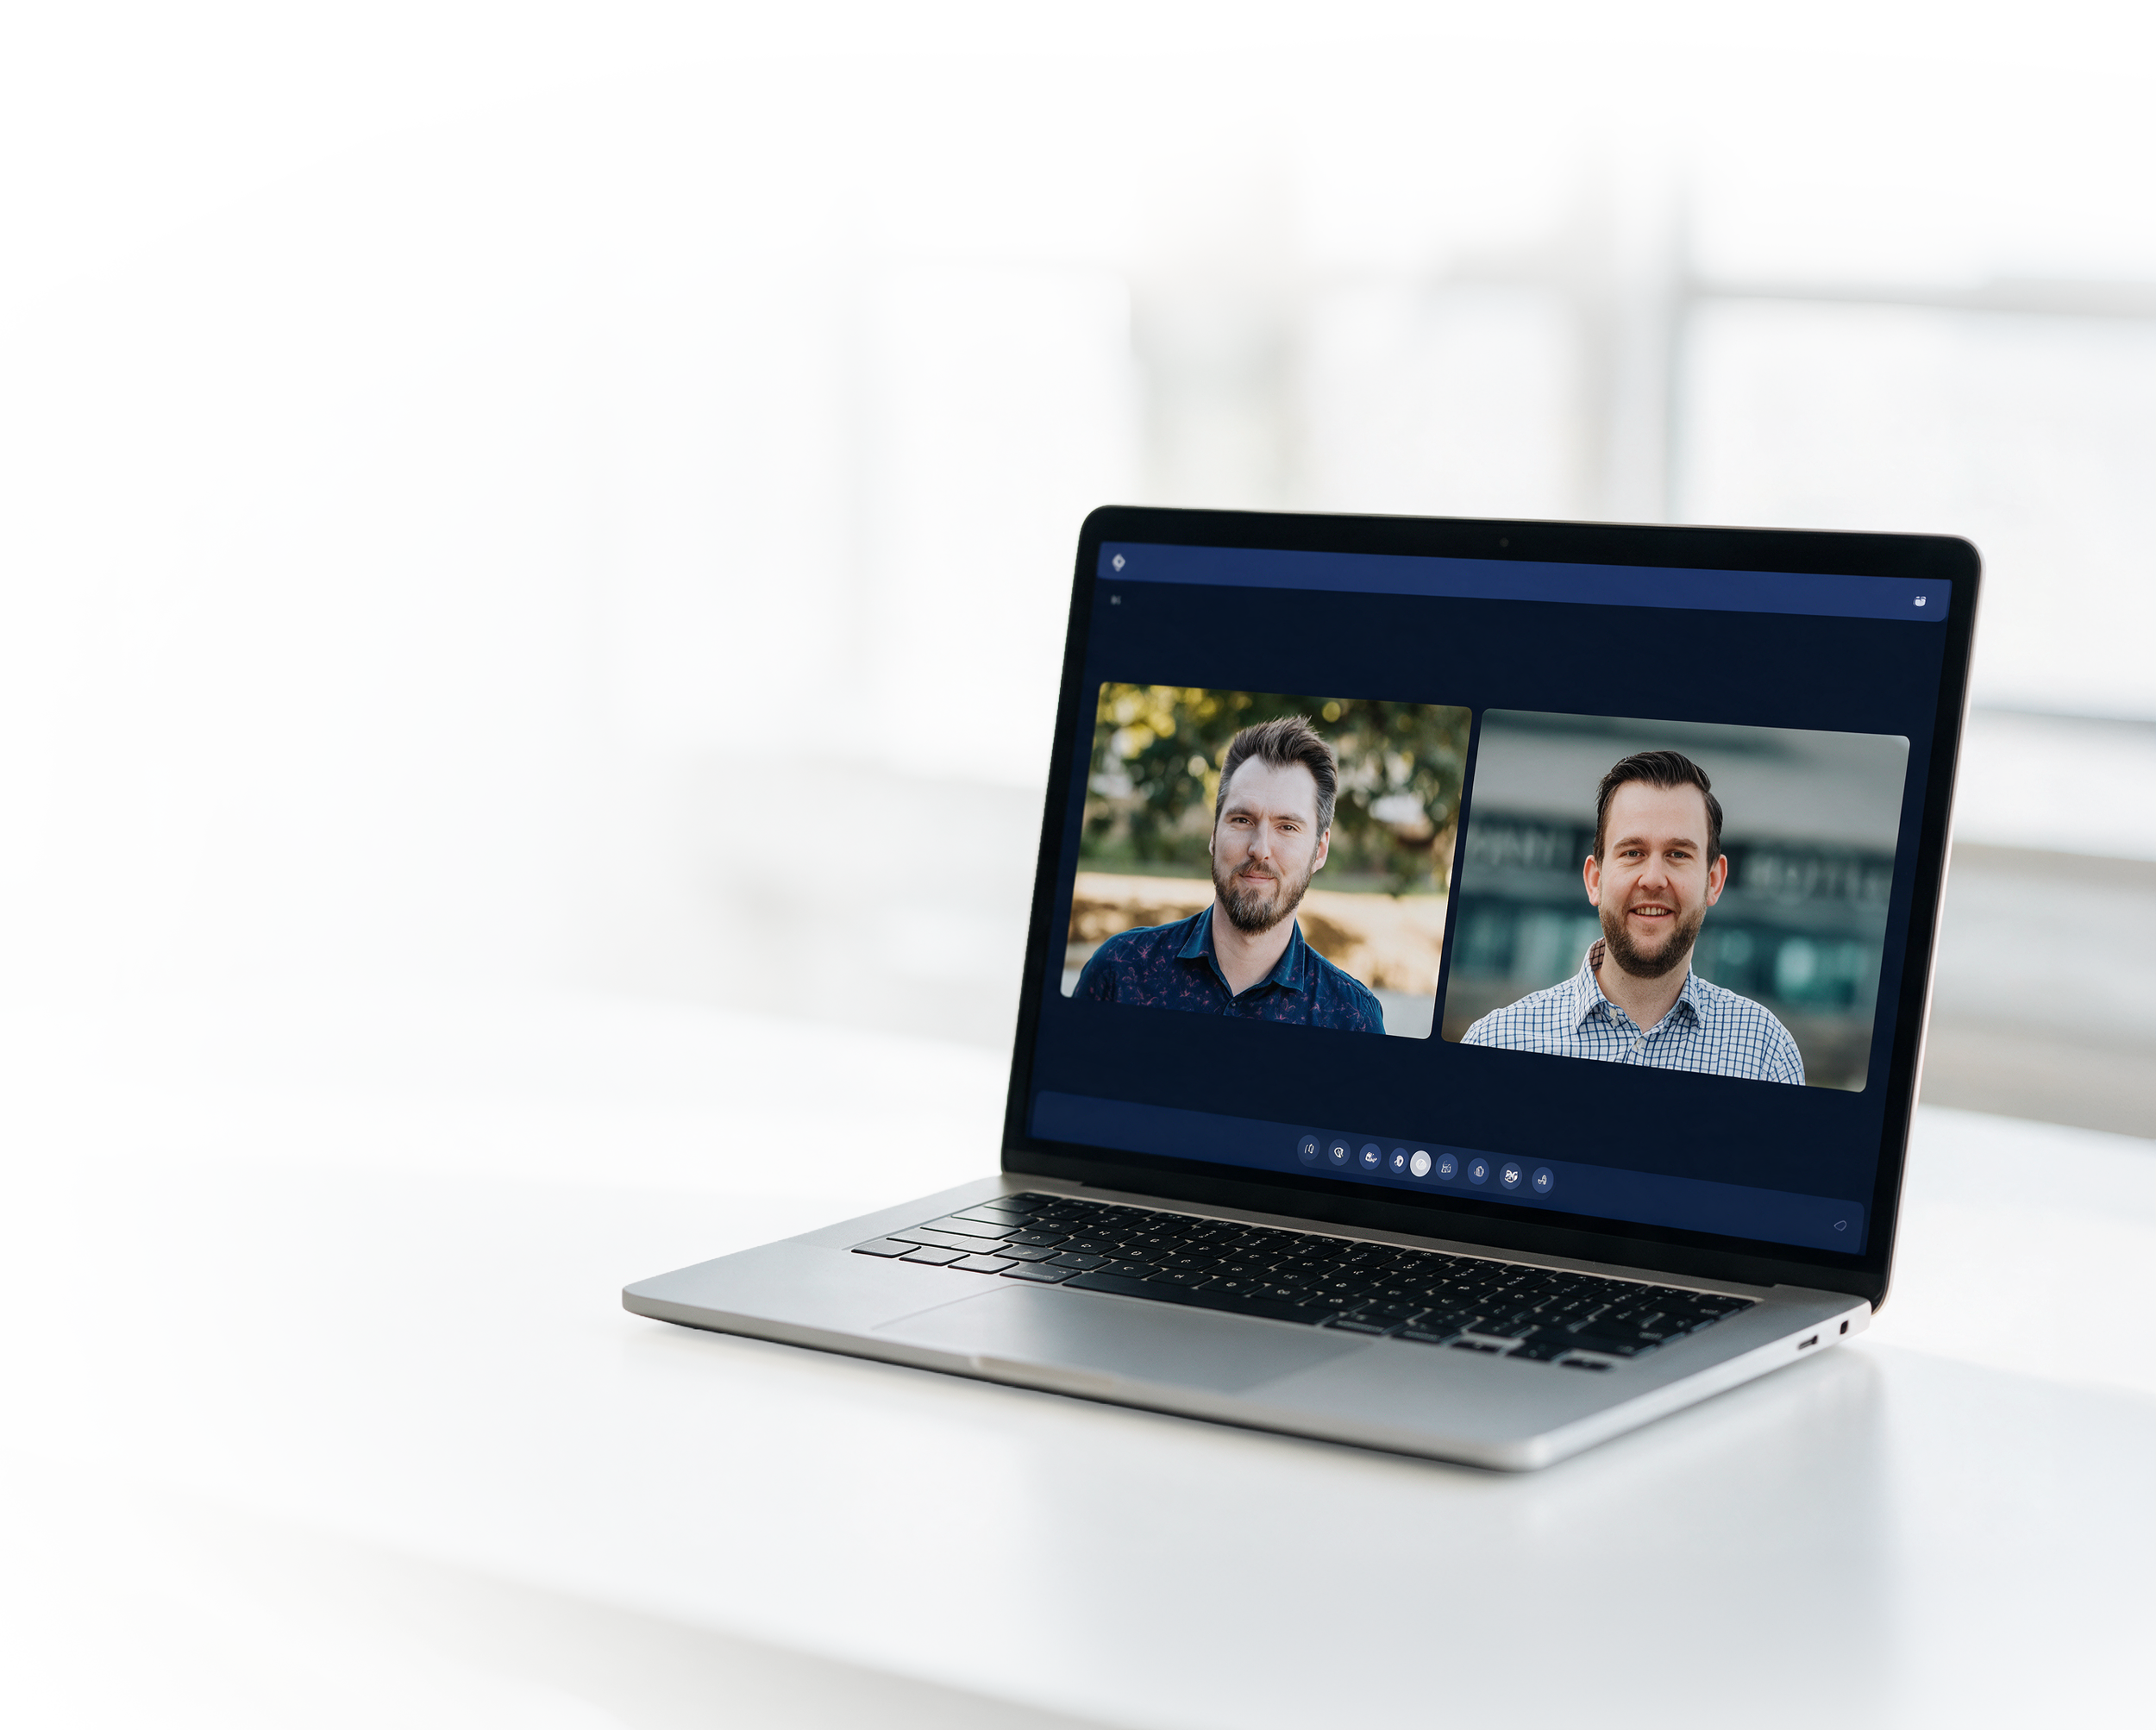
Reserve your place
Registration is free and takes under a minute.
Can’t join us live? Register anyway and we’ll send you the recording afterwards.

About the webinar
There’s a lot of noise around the latest tax changes, so let’s talk about what they could actually mean.
In June, Federal Parliament passed changes to how capital gains, investment property and SMSF borrowing are treated. A separate change to the way discretionary trusts are taxed is now before the Senate.
Instead of a formal presentation, Thomas Warner and Cameron Charles will sit down and talk it through, the way they would with a client across the table. They’ll cover what’s changing, the areas they’re keeping an eye on, and some of the questions clients are already asking.
The conversation will cover
- Capital gains tax: how the move from the 50% discount to cost base indexation and a 30% minimum tax will work from 1 July 2027
- Negative gearing: who is affected, who is not, and why 12 May 2026 matters
- SMSF borrowing: what the new limits on limited recourse borrowing arrangements mean for property in super
- Trusts: what we know so far about the proposed minimum tax on discretionary trusts
- The $1,000 standard deduction for work-related expenses, and who it suits
Trust tax: what we know so far
SPOTLIGHT
The proposed 30% minimum tax on discretionary trusts is now before Parliament. If passed, it would apply from 1 July 2028. Here is a snapshot of what Thomas and Cameron will unpack on the day.
The big picture
- Minimum 30% tax. Trustees of discretionary trusts would pay a minimum 30% tax on the trust’s taxable income.
- Non-refundable tax offsets. Individual beneficiaries would receive a non-refundable offset for the tax the trustee has paid. Company beneficiaries would not.
- Income thresholds. Beneficiaries on lower incomes may not be able to use the full offset, which could change the after-tax result of distributions to family members on lower tax rates.
Trusts outside the rules
- Fixed trusts are excluded. The Bill also proposes a new definition of a fixed trust, which may change which trusts qualify.
- Charitable trusts, special disability trusts, complying super funds, deceased estates and genuine testamentary trusts are also excluded.
Income outside the rules
- Primary production income: excluded. Farming income from carrying on a primary production business would not be subject to the minimum tax.
- Other income: rent, investment income and other business income would be subject to it. As drafted, this includes rent or agistment from simply holding farmland.
- A mix of both: trusts earning both types of income will need to separate them. This is where much of the complexity sits.
Three paths for existing trusts
- Restructure. Move assets into a company, fixed trust or other eligible entity using rollover relief, proposed from 1 July 2027 to 30 June 2030. Eligibility criteria apply, and state duties are a separate consideration.
- Elect to be an excluded election trust. Nominate beneficiaries and fixed shares of income. The minimum tax would not apply while the trust follows those nominations, but the trust gives up much of its flexibility.
- Stay as is. Keep the current structure and pay the minimum tax where it applies. For some families this will remain the right choice. For others, the extra tax may outweigh the flexibility.
The right path depends on the trust, the family and the type of income. That is what we will talk through on the day.
Bring your questions
Is there something you’d like us to cover? Let us know in advance and we’ll do our best to answer it on the day.
Send your questionYour hosts

Thomas Warner
Partner, Lincolns

Cameron Charles
Client Manager, Lincolns
Let’s Talk Tax: CGT, Trusts and What Might Be Changing
Thursday 26 November 2026 | 10.00am to 11.00am | Online webinar | Free event
Can’t join us live? Register anyway and we’ll send you the recording afterwards.

This information is general in nature and does not take into account your individual circumstances. Please speak with the Lincolns team before acting on the information.